Crypto gambling winnings are generally taxable in the United States. If a U.S. taxpayer wins Bitcoin, Ethereum, USDT, or another digital asset through gambling, the gambling income generally must be reported in U.S. dollars based on the value of what was received. A later sale, exchange, or other taxable disposition of the cryptocurrency can create a separate capital gain or loss.
The most important points for U.S. players are:
- Gambling winnings are taxable even when a casino pays in cryptocurrency.
- A casino does not have to issue Form W-2G for the income to be reportable.
- Crypto received as winnings should generally be valued in U.S. dollars when received.
- Selling or exchanging the crypto later may create an additional capital gain or loss.
- Beginning with the 2026 tax year, deductible gambling losses are generally limited to 90% of losses and cannot exceed gambling winnings.
- State gambling and cryptocurrency tax rules can add another layer to the federal rules.
For occasional players, the biggest mistake is treating Bitcoin casino winnings as taxable only when cryptocurrency is converted into dollars. U.S. federal tax rules generally do not work that way.
Are Crypto Gambling Winnings Taxable in the United States?
Yes. Gambling winnings are generally taxable income under U.S. federal tax rules, regardless of whether the player receives dollars, cryptocurrency, property, or another form of value.
The IRS states that gambling winnings must be reported even when they are not included on Form W-2G. Gambling income can include casino winnings, sports betting winnings, lotteries, raffles, poker and other wagering activities.
Cryptocurrency does not create a general exemption from those rules. Digital assets are treated as property for federal tax purposes, and taxable digital-asset transactions must generally be reported whether or not the taxpayer receives an information return.
This means that using a crypto casino does not automatically make gambling winnings tax-free or invisible for tax purposes.
How Are Bitcoin Casino Winnings Taxed?
Bitcoin casino winnings can potentially involve two separate tax calculations.
The first involves the gambling win itself. The second can occur when the Bitcoin is later sold, exchanged, or otherwise disposed of.
1. Gambling income when the Bitcoin is received
Suppose a player receives 0.05 BTC from a gambling withdrawal and the cryptocurrency attributable to taxable winnings has a fair market value of $5,000 when received.
The relevant gambling income is generally measured in U.S. dollars. Noncash gambling winnings are taken into account at fair market value, and IRS digital-asset guidance similarly uses U.S. dollar fair market value when determining income from digital assets received in taxable circumstances.
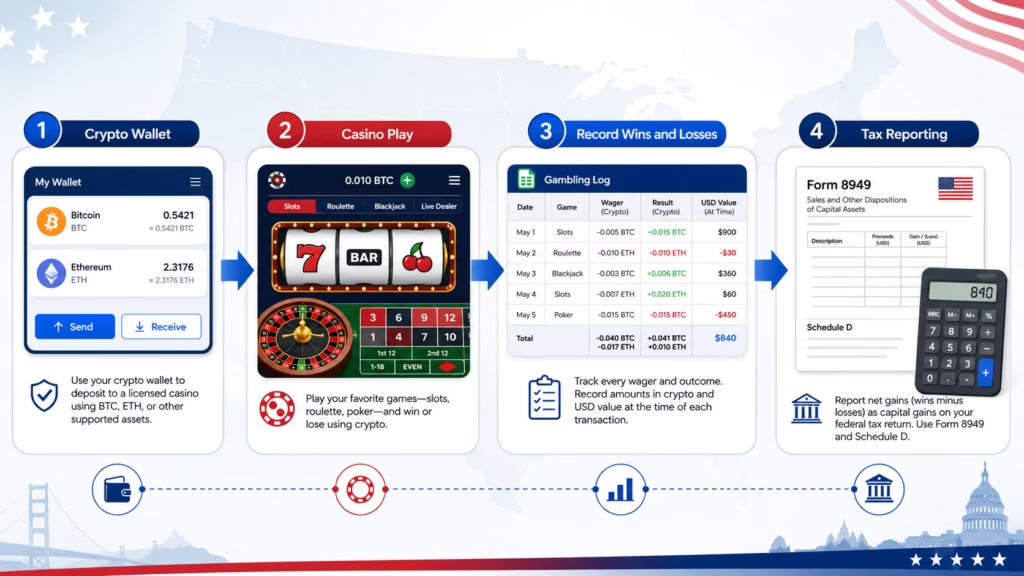
The player should therefore keep records showing the amount of cryptocurrency received, its USD value, the date and time, and the transaction associated with the payment.
2. Capital gain or loss when the Bitcoin is later disposed of
Receiving cryptocurrency and later disposing of it are separate events for tax purposes.
Assume the Bitcoin from the previous example has a relevant tax basis of $5,000 and the player later sells it for $6,000. The later transaction may produce a $1,000 capital gain.
If the Bitcoin instead falls in value and is sold for $4,000, the transaction may produce a capital loss, subject to the normal rules governing capital losses.
Individuals generally report applicable digital-asset capital transactions using Form 8949 and Schedule D unless an applicable reporting exception applies.
This distinction is critical. Paying tax on gambling income does not necessarily eliminate the need to calculate a later cryptocurrency gain or loss.
Do You Pay Tax Only When Crypto Is Converted to Cash?
No. Converting Bitcoin casino winnings into U.S. dollars is not necessarily the event that first creates taxable gambling income.
A player who receives cryptocurrency may already have a reportable income event before eventually selling the coins for dollars.
For example:
- A player receives gambling winnings worth $4,000 in Bitcoin.
- The player keeps the Bitcoin.
- Several months later, the Bitcoin is sold for $4,700.
The gambling portion and the later cryptocurrency appreciation should not automatically be treated as one $4,700 gambling win. The transaction can involve gambling income measured when the winnings are received plus a separate $700 gain from the subsequent change in Bitcoin’s value.
Accurate timestamps and USD valuations therefore matter much more for crypto gambling than for an ordinary cash casino withdrawal.
Do You Have to Report Crypto Gambling Winnings Without a W-2G?
Yes. Form W-2G reporting requirements and a taxpayer’s obligation to report taxable gambling income are not the same thing.
The IRS states that gambling winnings must be reported even if the player did not receive Form W-2G.
This matters with offshore and crypto-focused gambling sites because a player may receive no U.S. tax document at all.
The absence of a W-2G should not be interpreted as confirmation that the winnings are tax-free.
For 2026, the minimum reporting threshold applicable to certain Form W-2G payments increased to $2,000, although the exact reporting requirements still depend on the type of gambling and, for some wagers, the relationship between the payout and the amount wagered.
Certain gambling winnings may also be subject to 24% federal withholding. Withholding is only a prepayment toward federal taxes. It is not necessarily the player’s final effective tax rate.
Can Crypto Gambling Losses Be Deducted?
Gambling losses can potentially be deducted, but a major federal rule changed for tax years beginning in 2026.
For 2026, the gambling loss deduction is limited to the lesser of:
- 90% of gambling losses, or
- total gambling winnings.
The deduction generally requires itemizing deductions rather than simply subtracting all gambling losses from winnings on the income line.
The 90% rule can create taxable gambling income even when a player’s actual gambling result for the year is approximately break-even.
Example of the 2026 gambling loss rule
Suppose a casual gambler has:
- $10,000 of gambling winnings
- $10,000 of documented gambling losses
Under the 2026 federal limitation, 90% of $10,000 is $9,000.
The maximum loss deduction in this simplified example would therefore be $9,000 rather than $10,000. That can leave $1,000 of net taxable gambling income effect even though the player economically lost and won the same amount.
Now assume the player has:
- $10,000 of winnings
- $8,000 of losses
Ninety percent of the $8,000 losses is $7,200. In this simplified example, the allowable deduction would be $7,200, leaving a $2,800 difference between reported winnings and the gambling-loss deduction.
The exact tax impact depends on the rest of the taxpayer’s return, filing status and itemized deductions.
What Records Should Crypto Gamblers Keep?
Crypto gambling creates an unusual recordkeeping problem because casino activity and blockchain transactions may need to be reconciled.
A useful gambling record should include:
- date and time of wagers and gambling sessions;
- casino or sportsbook name;
- game or type of wager;
- amounts wagered;
- gambling winnings;
- gambling losses;
- cryptocurrency and quantity received;
- USD value of relevant cryptocurrency transactions;
- wallet transaction IDs;
- casino account statements;
- deposit and withdrawal records;
- exchange records showing later sales or conversions.
Taxpayers claiming gambling losses should maintain records supporting both winnings and losses. Receipts, statements and similar evidence can be important if a deduction is questioned.
For cryptocurrency, recordkeeping also helps establish basis when a digital asset is eventually sold, exchanged or otherwise disposed of.
Does Moving Crypto Between Wallets Create Another Tax?
A genuine transfer of cryptocurrency between wallets owned by the same taxpayer is generally different from selling or exchanging the asset. However, players need enough documentation to demonstrate that a transaction was actually a transfer rather than a disposition.
Casino deposits and withdrawals can be more complicated than straightforward self-to-self wallet transfers because the cryptocurrency is interacting with another party and may be connected with wagering transactions.
Players with significant activity should avoid assuming that every blockchain transaction can be classified solely from the wallet address. Transaction history, ownership and the economic purpose of the transfer matter.
For complex crypto gambling histories, a CPA or tax professional familiar with both gambling and digital assets can be useful.
Does Using Crypto to Gamble Create a Taxable Crypto Transaction?
Potentially. Cryptocurrency held as an investment is generally treated as property, and selling, exchanging, or otherwise disposing of a digital asset can create a taxable gain or loss.
Sales, exchanges for other digital assets, exchanges for goods or services and other dispositions of digital assets may require tax reporting.
The precise treatment of cryptocurrency transferred into a gambling transaction can depend on the structure of the transaction and the taxpayer’s circumstances. Players should therefore be cautious about assuming that only withdrawals matter for cryptocurrency tax purposes.
This is especially important for players who originally acquired Bitcoin at a much lower price than its value when they began using it for gambling.
Federal Taxes vs State Taxes on Crypto Gambling
Federal treatment is only part of the calculation.
State rules for gambling income, gambling-loss deductions and cryptocurrency can vary substantially. Some states impose an individual income tax, while others do not. States can also differ in how closely they follow federal deductions and gambling rules.
A player should therefore check the rules for the state in which they are considered a resident and any other state that may have a claim to the gambling income.
The location of a crypto casino’s servers or corporate registration does not by itself determine a U.S. taxpayer’s entire state or federal tax position.
What About Offshore Crypto Casinos?
Using an offshore crypto casino does not automatically eliminate U.S. federal reporting obligations.
U.S. taxpayers are generally taxed according to U.S. tax rules applicable to their income, not simply according to whether a gambling operator sends U.S. tax paperwork.
Tax compliance and gambling legality are also separate questions. Reporting gambling income does not establish that an operator is legal or authorized to accept players in a particular state.
Before using a crypto gambling site, players should independently check local gambling restrictions, operator availability and applicable tax obligations.
Common Crypto Gambling Tax Mistakes
The biggest errors usually come from treating cryptocurrency and gambling as a single tax event.
Common mistakes include:
- reporting winnings only after cryptocurrency is converted into dollars;
- assuming no W-2G means no taxable income;
- reporting only net cash withdrawn from the casino;
- failing to record the USD value of cryptocurrency when relevant transactions occurred;
- ignoring later gains or losses on Bitcoin received from gambling;
- failing to document gambling losses;
- assuming 100% of gambling losses remain deductible in 2026;
- mixing casino wallets, personal wallets and exchange accounts without keeping transaction records;
- assuming offshore gambling sites are outside U.S. tax rules.
Good records are considerably easier to create while gambling activity is occurring than months later when preparing a tax return.
How to Handle Crypto Gambling Taxes More Safely
For occasional players, the practical approach is to maintain a gambling ledger alongside cryptocurrency transaction records.
Each significant casino transaction should be matched with its date, cryptocurrency quantity and USD value. The records should also separate gambling results from subsequent price changes in the cryptocurrency itself.
Players with high transaction volumes, multiple wallets, DeFi activity, multiple casinos, professional gambling activity, or large gains should consider professional tax advice. Those situations can create issues beyond the basic casual-gambler rules described here.
Taxes should also be considered before spending the entire gambling withdrawal. Certain taxpayers with gambling income may need to make estimated tax payments if insufficient tax has been withheld.
Gambling itself should be treated as entertainment rather than a reliable method of producing income. Cryptocurrency does not change the randomness or financial risk of casino games.
How This Information Was Reviewed
This guide applies the IRS rules for gambling income together with current federal guidance covering digital assets, basis, capital transactions and Form W-2G reporting.
Special attention is required for 2026 because federal law changed the gambling-loss deduction to 90% of qualifying losses, subject to the limitation based on gambling winnings.
Tax outcomes can still differ based on filing status, state residence, professional versus casual gambling status, transaction history and the way cryptocurrency was acquired or disposed of. Players dealing with substantial amounts should verify their situation against current IRS guidance and, where appropriate, obtain advice from a qualified U.S. tax professional.
FAQ
Do you have to pay tax on crypto gambling winnings in the USA?
Yes. U.S. gambling winnings are generally taxable even when they are paid in Bitcoin, Ethereum, stablecoins or another digital asset. The fact that payment occurs in cryptocurrency does not create a general federal gambling-income exemption.
Are Bitcoin casino winnings taxable if I never sell the Bitcoin?
Potentially yes. The gambling income generally does not depend solely on whether you later convert the Bitcoin to dollars. A later sale or exchange can then create a separate cryptocurrency gain or loss.
Does an offshore crypto casino report winnings to the IRS?
Reporting practices vary, but the player’s federal tax obligation does not depend entirely on whether the casino provides a U.S. information return. Taxable gambling winnings generally remain reportable even when no Form W-2G is received.
How do I calculate the value of crypto gambling winnings?
The relevant cryptocurrency should generally be valued in U.S. dollars using an appropriate fair market value at the applicable time. Keep records showing the asset, quantity, timestamp and valuation source so the amount can later be reconstructed.
Can I deduct 100% of my gambling losses in 2026?
Generally no. Beginning in 2026, the federal deduction is limited to 90% of gambling losses and cannot exceed gambling winnings. Casual gamblers generally must itemize to claim the deduction.
What happens if I win and lose the same amount gambling in 2026?
You can still potentially have taxable gambling income effect. For example, $10,000 of winnings and $10,000 of losses produces a maximum loss deduction of $9,000 under the 90% federal rule, assuming the deduction is otherwise available.
Do I owe capital gains tax on Bitcoin casino winnings?
A separate capital gain can arise if cryptocurrency received through gambling later increases in value and is sold or otherwise disposed of in a taxable transaction. A decline in value may instead produce a capital loss, subject to the normal capital-loss rules.
Is Form W-2G required for all crypto casino winnings?
No. Form W-2G requirements depend on the amount, type of gambling and other reporting conditions. However, the absence of a W-2G does not remove the obligation to report taxable gambling winnings.
Do crypto gambling taxes differ by state?
They can. State income-tax rules, gambling deductions and treatment of gambling income differ across jurisdictions. A federal calculation should therefore not automatically be assumed to produce the same result on a state return.
Should I use crypto tax software for casino transactions?
Crypto tax software may help organize wallet transactions and calculate digital-asset gains and losses, but it may not correctly understand the gambling character of every casino deposit, wager or withdrawal. High-volume or complicated activity may require manual reconciliation or professional review.
Brief Conclusion
Crypto gambling winnings are generally taxable in the United States even when paid in Bitcoin or another digital asset. Players may need to account for both gambling income and later cryptocurrency capital gains or losses.
The most important 2026 change is the federal gambling-loss rule. The deductible amount is generally limited to 90% of gambling losses and cannot exceed gambling winnings. Because crypto casinos often provide less conventional tax documentation, keeping detailed records of wagers, withdrawals, cryptocurrency values and later asset disposals is especially important.